
Crypto POS With PIN Cashiers: Know Who Rang What at Shift Close
Key takeaways
- Every cashier signs into the Payzum POS with a personal PIN, so each sale has a name on it. Nobody has to guess who rang something up at closing time.
- Adding a cashier means adding a PIN. It does not mean another leased terminal, another software seat or another acquirer form.
- Per-cashier and per-terminal analytics turn the shift close into a report: who took what, on which device, at what time.
- The cashier rings the sale but never holds the money. Each payment settles in seconds (Solana about 0.4 s, Base and Polygon about 2 s) to your own wallet, and an on-chain payment cannot be charged back.
Five people on shift, one login, no names
Most small teams run payments the same way. There is one card terminal at the counter, one shared login if there is a login at all, and everyone on shift uses it. The terminal knows a payment happened. It has no idea who took it.
Attribution then lives in a side system: initials on tickets, a shared spreadsheet, memory. Reconciliation happens at 11 p.m. with a calculator and whoever closed.
Proper per-employee tracking usually sits in the mid or top tiers of POS software, billed monthly and often per register. So owners choose between paying software rent for accountability and going without it. Meanwhile each extra register is another bought or leased device, and the card stack underneath still charges a percentage plus a fixed fee on every tap. The Federal Reserve publishes the average debit interchange fee under Regulation II, and it is only one layer of what a merchant pays.
Weak attribution is not a small problem. The National Retail Federation's National Retail Security Survey put US retail shrink at $112.1 billion for 2022, and it attributed about 29% of it (28.85%) to internal theft. NRF has since stopped that annual survey, so treat the share as a 2022 data point. Its direction is still clear: a large slice of loss comes from people inside the business, and it is hardest to trace when the register does not know who stood at it.
What untracked registers cost a small team
Start with time. A close that matches terminal batches against tickets against the till eats 20 to 40 minutes a night. Over a year that is a part-time salary spent producing a number you still do not fully trust.
Then the leaks. The Association of Certified Fraud Examiners' 2024 Report to the Nations covers 1,921 cases. Skimming shows up in 10% of them with a median loss of $43,000, and register disbursements in 3% with a median of $50,000. The report also finds skimming more common in smaller organizations. A small shop rarely has a second pair of eyes on the till.
Without attribution, every discrepancy becomes a house loss by default. It could be a discount nobody approved, a sale rung as a cheaper item, or a payment that never came through. You cannot ask a fair question about a pattern you cannot see.
Then the bottleneck. At Saturday peak, three capable staffers funnel every customer through one terminal, because giving each of them a register means hardware, seats and setup you never got to. And when a card dispute lands weeks later, it arrives with no name on it either: money pulled back, a fee attached, and no way to connect it to a shift.
Why card rails put a price on knowing who took the money
This is not bad software. It follows from how card acceptance is built. The unit of a card system is the certified device on a merchant account. The acquirer underwrites a business and its terminals, not the people who use them.
Anything person-shaped, such as logins, permissions and per-employee reports, gets bolted on by POS software. That is why it is sold as a subscription tier rather than a property of the payment.
Add the reversibility of cards. Under Visa's rules the issuer generally has 120 days from the processing date to raise a dispute, and some conditions run longer. So the stack tells you who took the money only if you pay for it, and the money is never quite final. A crypto payment flips the unit. Each sale is one on-chain push to your wallet, so attaching an identity to it is just software, and the settlement is already final.
How a PIN cashier takes a payment on Payzum
Payzum is a non-custodial, crypto-only payment processor, and its point of sale treats staff as first-class users. Each employee gets their own PIN login. They sign in on any phone, tablet or physical terminal and enter the amount. The screen shows a fresh QR generated for that exact sale.
The customer scans it with any wallet and pays. The payment confirms on-chain in seconds, about 0.4 s on Solana and roughly 2 s on Base or Polygon across the supported networks, and lands in a wallet your business controls.
That changes what trusting staff with payments means. Your cashiers ring up sales but never hold funds. There is no drawer to skim, no card number passing through their hands, and no Payzum balance either. What staff produce is data: per-cashier and per-terminal analytics record who rang what, on which device, and when.
Scaling follows the roster, not the hardware budget. One account runs as many PIN cashiers and devices as you need, so a second register at rush hour is a staffer's phone and their PIN (see turning any phone into a crypto POS). Quote prices in dollars, and optional auto-convert settles each sale as USDC or USDT.
Payzum charges 0.5% per processed sale, deducted from the amount received, plus on-chain network gas. A customer who pays 100 leaves you 99.50. The account has 2FA and a full audit log. If the model is new to you, start with how non-custodial processing works or the broader guide to accepting crypto payments in person.
Setting up your team, one PIN at a time
- Create your Payzum account. Sign up for the business. There is no acquirer application, no per-register contract and no software tier to pick before you can add staff.
- Connect a wallet you control. Point settlement at your business wallet on the networks you want to accept, and turn on auto-convert if you want every sale to land as USDC or USDT.
- Create a PIN login for each staffer, then open the POS on every phone, tablet or terminal that will take payments. Each device becomes a tracked register on the same account.
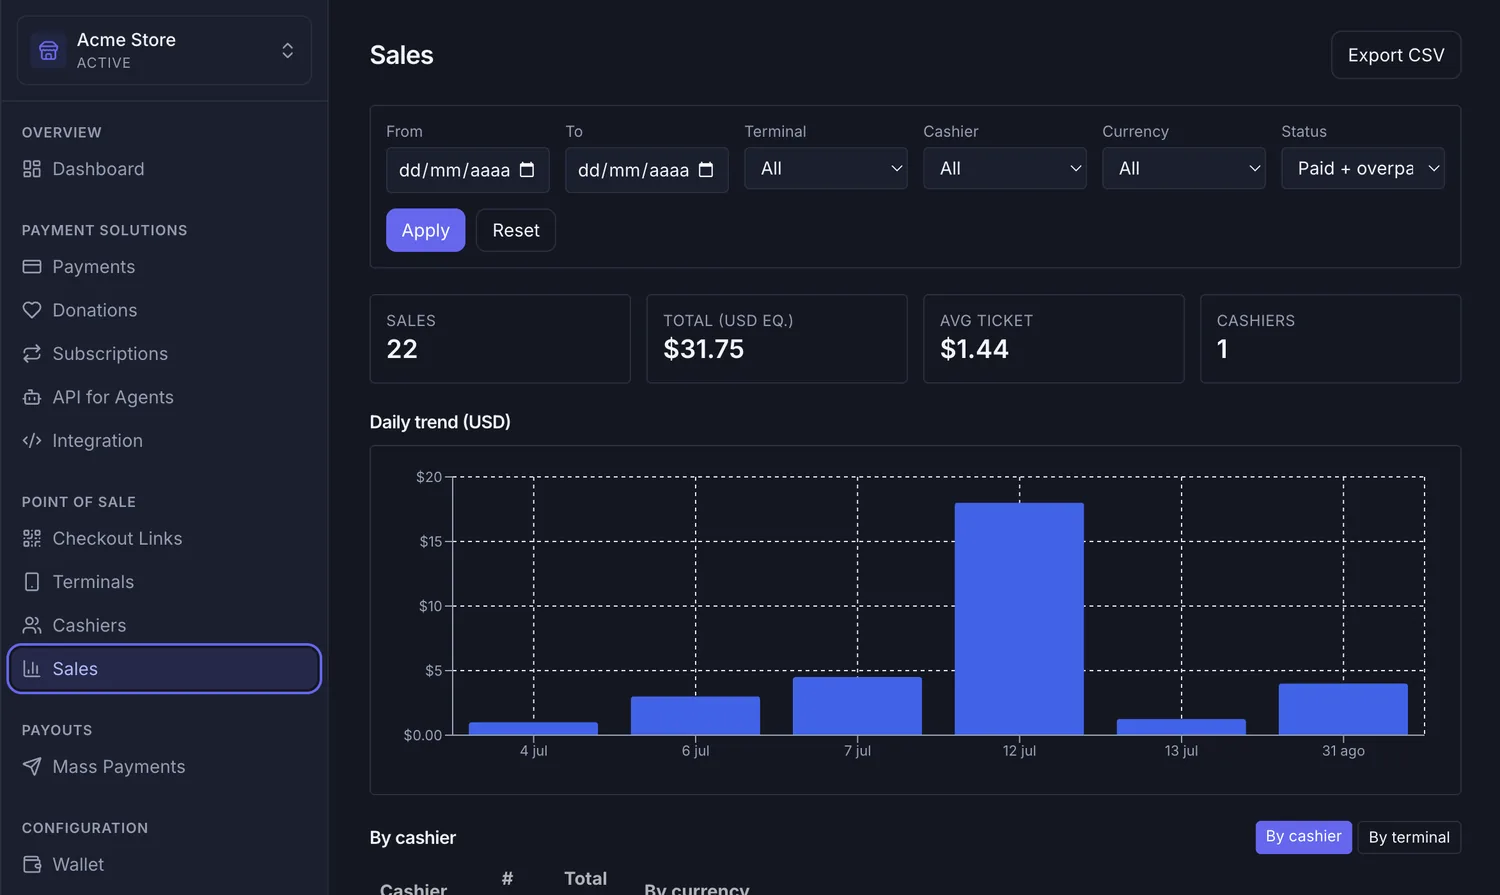
- Sell, then close the shift from the dashboard. Cashiers sign in with their PIN and ring up sales as fresh QRs. At close, the per-cashier and per-terminal view shows who took what.
A Saturday shift in numbers: three PINs, one report
Here is a hypothetical café (round numbers, not a customer) with three cashiers on a busy Saturday. Each one signs in on their own phone with a PIN. At close, the dashboard breaks the day down like this:
| Cashier (PIN) | Sales | Total | Average ticket |
|---|---|---|---|
| Ana | 61 | $1,342 | $22.00 |
| Ben | 48 | $1,013 | $21.10 |
| Cleo | 33 | $645 | $19.55 |
| All three | 142 | $3,000 | $21.13 |
The 0.5% fee on $3,000 is $15, so $2,985 arrives in the café's wallet, before network gas. The check takes one minute: do the three totals add up to the wallet, and does any average ticket sit far from the others?
If Cleo's average were $9 instead of $19.55, the owner would have a specific, fair question for Monday morning (a discount habit? a training gap?). On a shared login that question cannot even be asked.
Where PIN cashiers earn their keep: six teams
- Café or restaurant at peak. Instead of one terminal-shaped queue, three staffers open the POS on phones with their own PINs. That makes three lanes at the Saturday rush with no extra hardware, and the owner sees each lane's take at close.
- Waiters collecting at the table sign in on their own device and ring the ticket there. The customer scans the QR before the server walks away, and the payment is attributed to the server who closed it.
- A retail shop with rotating shifts has morning and evening crews that share registers but never logins. When the till report and the sales report disagree, the per-cashier, per-terminal breakdown says where.
- A salon or barbershop gives each stylist their own PIN. The owner gets volume by chair, which helps with commission math and with spotting the quiet weekday nobody mentions.
- A food-truck fleet or market operator runs every stall as a terminal on one account. Per-terminal analytics compare locations side by side, and every stall settles to the same wallet.
- Drivers and field technicians collect at the door under their own PIN. The owner knows who collected what without holding anyone's cash, because nobody ever holds cash.
PIN cashiers against a card terminal with POS software
| What matters | Card terminal + POS software | Payzum PIN cashiers |
|---|---|---|
| Who took the sale | Shared device; staff tracking is a paid software tier | Every sale attributed through each cashier's PIN |
| Adding a register | Another device, seat and monthly fee | Another PIN on another phone |
| Shift close | Batches vs tickets vs till, by hand | Per-cashier, per-terminal report from the dashboard |
| Where funds sit | Acquirer batch, 1 to 3 days out, reserves possible | Your own wallet, in seconds; staff never touch funds |
| Disputes | Issuer can reverse for about 120 days, with no staff attribution | On-chain finality, no chargebacks |
| Cost per sale | A card percentage plus a fixed fee per sale, plus the software seat | 0.5% of the sale, deducted from the amount received, plus network gas |
| Price stability | Fiat, minus the fee stack | Auto-convert settles as USDC/USDT |
Objections from owners with a payroll
Isn't giving staff access to payments a security risk?
It is the opposite of the cash drawer problem. A PIN cashier can ring up sales and nothing else. Funds settle non-custodially to the business wallet, so no staffer holds money, sees a card number or touches a balance. The wallet keys stay with the owner, the account runs 2FA, and the audit log records every action under the PIN that performed it.
Do I need a separate wallet or account per employee?
No. You need one business account and one settlement wallet per network, with as many PIN cashiers as you have staff. A PIN identifies a person for login and attribution. It is not a wallet.
My customers pay by card. Will anyone actually use this?
Run it beside the card terminal, not instead of it. It helps most where cards are weakest: the second and third lane at rush, tourists whose foreign cards decline, crypto-holding regulars, and small tickets that a fixed fee punishes. Staff reporting comes with it.
If payments are final, how do refunds work?
A refund becomes a deliberate action from your own wallet, on your own policy. The audit trail tells you which cashier took the original sale and when. What disappears is the involuntary version, a dispute that pulls money back months later with a fee and no context.
Frequently asked questions
What is a crypto POS with PIN cashiers?
It is a point of sale where each staff member signs in with a personal PIN to take crypto payments. In Payzum, every sale a cashier rings up is a fresh QR the customer pays from any wallet. The payment settles in seconds to the business's own wallet, and per-cashier and per-terminal analytics attribute every sale to the person who took it.
How many cashiers and devices can share one Payzum account?
As many as your business needs. Each staffer gets their own PIN login, and the POS runs on any number of phones, tablets or physical terminals under the same account. Each one shows up separately in the analytics.
Can my staff access the business's funds?
No. PIN cashiers can ring up sales, but settlement is non-custodial: payments go straight from the customer's wallet to a wallet only the business controls. Staff never hold funds, and the owner's account is protected with 2FA and a full audit log.
What do per-cashier analytics actually show?
Sales broken down by cashier and by terminal: who rang what, on which device, and when. Shift closes and reconciliation become reading a report instead of matching terminal batches against tickets by hand.
Which networks can customers pay on, and how fast is settlement?
Payzum supports Bitcoin, Ethereum, Solana, Polygon, Base, Arbitrum, Optimism, BNB Chain and Avalanche. Confirmations take about 0.4 seconds on Solana and around 2 seconds on Base or Polygon, and optional auto-convert settles every sale as USDC or USDT.
Can a customer reverse a payment a cashier took?
No. On-chain settlement is final and there is no chargeback mechanism, so a confirmed sale cannot be pulled back weeks later the way a card payment can for roughly 120 days.
Book a meeting and bring your roster
Tell us how your team takes money today, whether that is one shared terminal, a till, servers on the floor or stalls across town. We will design your crypto POS around it: a PIN login per staffer, a fresh QR per sale, per-cashier and per-terminal analytics, optional auto-convert to USDC or USDT, and non-custodial settlement in seconds to a wallet you control on the networks your customers use. If you also sell online, the same account adds payment links, invoices and hosted checkout settling to the same wallet.
Prefer a direct link? Book a payments consultation · [email protected]